A joint account for couples is a bank account both partners own and can access, and it’s one of three ways couples organize money: fully joint, fully separate, or a hybrid of the two. There’s no single right setup. The best structure depends on your income, expenses, debt, legal status, and how much independence each of you wants to keep.
Whichever way you lean, you’re in good company. Research by Gladstone, Garbinsky, and Mogilner found that long-term couples who pool all their money into joint accounts report higher relationship satisfaction (UCLA Anderson Review). Yet U.S. Census Bureau data shows more married couples keeping at least some money separate than a generation ago. Both things can be true because, in our view, the account structure matters less than whether both partners understand and agree on it.
This guide compares joint, separate, and hybrid setups, walks through the pros and cons of a joint account, and gives you the questions to talk through before you open one – whether you’re married or not. (For the bigger picture the account sits inside, see financial planning for couples and setting money goals with your partner.)
Key takeaways
- Couples organize bank accounts three ways: fully joint, fully separate, or a hybrid with one shared account for household bills and individual accounts for personal spending.
- According to 2023 U.S. Census Data, 49% of couples combine everything, 17% use a hybrid setup, and 23% keep finances fully separate.
- A joint account simplifies shared bills and goals, and it doubles FDIC coverage – the FDIC insures two co-owners up to $500,000 in the joint ownership category at one bank.
- The tradeoff is access. Either owner can move money without the other’s approval, and a creditor of either partner can try to collect from the account.
- You don’t need to be married to open a joint account, but unmarried couples should be extra clear about contributions, withdrawals, and what happens if the relationship ends.
- The right setup is the one both partners understand, agree to, and can actually maintain – and you can change it as your life changes.
What is a joint bank account?
A joint bank account is a checking or savings account that two or more people own together. According to the Consumer Financial Protection Bureau, “generally, everyone whose name is on a joint account can write checks, withdraw money, make transactions, move funds, or close the account.”
Questions to ask before opening a joint bank account
A few honest conversations up front beat months of “who paid what” later. Talk through these together before you pick a structure.
Are you married, unmarried, or planning to be?
Legal status changes what happens to shared money if the relationship ends. If you’re married, state law shapes how assets divide. IRS Publication 555 lists nine community property states. In California, one of them, a judge will generally divide community property equally, according to California Courts. Many other states, Alaska for example, divide property in a “fair and equitable way,” as the Alaska Court System puts it.
A prenuptial agreement can change either outcome. If you’re not married, divorce property rules generally don’t apply, according to LawHelp Minnesota. That can make untangling a shared account harder, not easier.
How much financial history is each of you bringing in?
Combining accounts is usually simpler early in your financial life. It gets more emotionally complicated when one or both of you have decades of savings, investments, property, or a business – especially if net worth is uneven. Plenty of couples who combine later in life choose a hybrid setup for exactly this reason.
Does either of you have significant debt?
Splitting rent is one decision; paying down a partner’s student loans is another. Put every balance on the table – credit cards, student loans, auto loans, and medical debt – and decide together whether repayment comes from shared money or stays with the person who took it on. Neither answer is wrong. Not discussing it is.
Do you earn very different incomes?
If one of you earns substantially more, decide whether you’ll split bills 50/50, proportionally by income, or by assigning specific expenses to each person. A proportional split keeps contributions fair without requiring identical dollar amounts.
Who’s going to be the day-to-day money manager?
In most households, one person naturally watches the balances and makes sure bills go out on time. That’s fine as long as both partners can see the full picture and stay involved in the big decisions. A shared view of your household budget keeps the less hands-on partner informed without turning them into a bookkeeper.
How much independence does each of you want?
Some couples want full visibility into every dollar. Others want personal spending to stay personal. The goal is a setup that supports trust without making either partner feel monitored – and only the two of you can decide where that line sits.
Joint, separate, or hybrid: Three options for couples
Most couples’ setups fit one of three patterns. Each works; each demands a different level of coordination.
Account setup | How it works | Best for | Watch out for |
Fully joint | Most or all income lands in shared accounts; bills, goals, and personal spending come from one pot | Couples who want maximum visibility and treat money decisions as shared | Either owner can move money unilaterally; uneven spending habits share one pot |
Hybrid | One shared account covers household bills; individual accounts hold personal money | Couples who want transparency on shared costs and autonomy everywhere else | Requires agreement on who contributes how much and recalculating when income changes |
Fully separate | Each partner keeps individual accounts and owns specific shared bills | Couples who value independence or combined finances later in life | Bills can slip through the cracks without steady communication |
Here’s how each looks in practice – including how real Monarch member households split.
Option 1: The “All-In” method

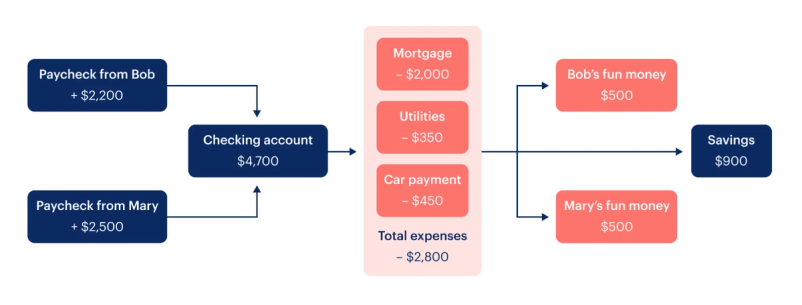
How it works:
- Each partner’s income goes into a shared checking account.
- All shared bills, everyday expenses, and savings goals are paid from that account.
- Each person gets an agreed amount of “fun money” for no-questions-asked personal spending.
- The rest goes to savings.
This is the simplest structure and the most common one: 55% of Monarch member couples combine everything. One pool of money means one budget, one set of balances, and no math about whose turn it is to pay.
A good fit if you:
- Want one shared household budget with full visibility for both partners
- Have large fixed costs to cover reliably, like childcare, a mortgage, or saving for a house
- Earn similar incomes, or genuinely don’t care who appears to “pull their weight”
- Combined finances early, before either of you built a complex money life
Think twice if you:
- Value individual financial independence, especially if you’re combining later in life
- Have a partner who won’t track spending; one pot amplifies that friction
- Don’t want a spouse to receive some or all of your money if something happens (see account types below)
Option 2: The “Proportional” method

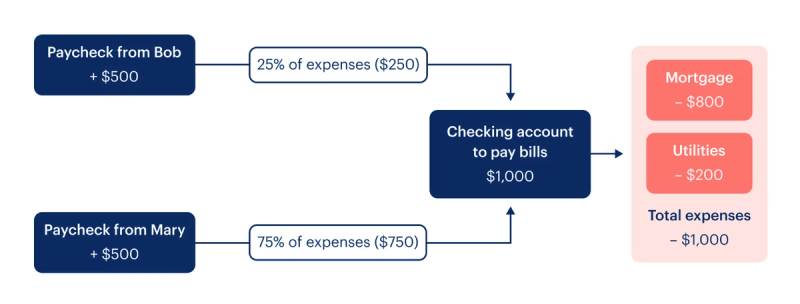
How it works:
- Income lands in each partner’s individual account.
- Both partners fund a shared account for household bills in proportion to income. If one of you earns 60% of household income, you cover 60% of the bills.
- Whatever’s left stays in individual accounts as personal money.
This hybrid keeps autonomy and still guarantees the essentials are covered. 18% of Monarch member couples use a version of it – some accounts combined, others separate. It’s especially useful when incomes differ, because contributions feel proportional instead of strictly equal.
A good fit if you:
- Want to test combining finances gradually
- Have a large income difference and want the split to feel fair
- Want shared visibility on household bills but personal spending kept personal
Think twice if you:
- View marriage as fully “two become one” – this setup will feel like accounting
- Don’t want to recalculate contributions every time income changes
- Struggle to agree on which expenses count as “shared”
A hybrid setup runs on one shared picture of income, bills, and leftovers. That’s easier with a household view of your accounts than with weekly spreadsheet archaeology.
Option 3: The “Divide and Conquer” method

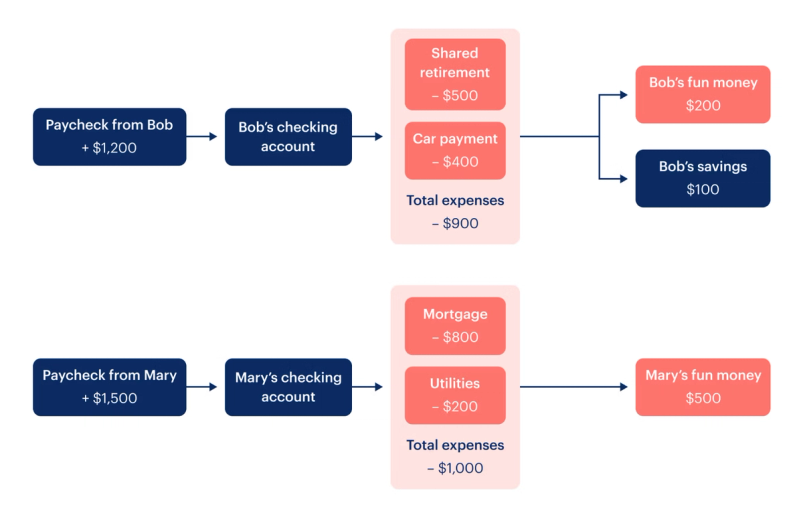
How it works:
- Income stays in individual accounts.
- Each partner owns 100% of specific shared expenses; one covers rent, the other covers utilities and groceries, and so on.
- Personal spending stays completely separate.
This is the most independent structure, and it’s a real pattern, not an outlier: 12% of Monarch member couples keep finances fully separate. Some also hold shared investments, like a joint brokerage account – if you do, make sure your partner is listed for ownership should something happen to you.
A good fit if you
- Prefer not to combine finances but still share a household
- Combined finances later in life and want prior assets and earnings kept separate
- Communicate clearly and consistently about who pays what
Think twice if you:
- Want visibility into how each other spends
- Have variable income that could leave an assigned bill unpaid
- Find it hard to talk about money habits – this setup needs the most coordination of the three
If you keep money mostly separate, regular money check-ins matter more, not less. A monthly money date to review bills, balances, and goals keeps a separate setup from becoming a siloed one.
Pros and cons of joint bank accounts for couples
A joint account simplifies shared money and changes who has access to it. Both halves of that sentence matter.
Pros | Cons |
Pays rent, utilities, childcare, and other shared bills from one place | Either owner can move money without the other’s approval |
Speeds progress on shared goals, from an emergency fund to a down payment | A partner’s creditors can try to collect from the shared balance |
Ends “who paid what” debates, since both partners see the same balances | Gets messy in a split if no one documented ownership and legal status |
Doubles FDIC coverage: the FDIC insures two co-owners up to $500,000 at one bank | Feels disruptive if one partner values financial independence |
Supports clear rights of survivorship when set up correctly | Puts uneven spending habits in one shared pot |
A joint account works best when both partners agree on what it’s for, how much each person contributes, and which expenses it covers; decisions worth making before the first deposit, ideally alongside a shared budget.
How couples actually handle joint and separate accounts
It’s rare to see inside another household’s money setup, which makes it hard to know what’s “normal.” The data says: there is no normal – but the mix is shifting.
- 77% of married couples with bank accounts held at least one joint account in 2023, down from 85% in 1996, according to the U.S. Census Bureau.
- The share of couples holding all their bank accounts jointly fell from 53% to 40% over that period. The share with both joint and separate accounts (the hybrid approach) rose from 9% to 17%.
- Fully separate finances rose too: 23% of married couples with bank accounts had no joint account in 2023, up from 15% in 1996.
- Among unmarried couples living together, just 16% held a joint account, rising to 25% for those living with minor children.
Separate accounts aren’t a red flag, and joint accounts aren’t a loyalty test. What matters is whether both partners understand the setup and have enough visibility to make decisions together.
Types of joint accounts couples can open
Not all joint accounts treat ownership the same way. “Rights of survivorship” – who receives the money if one owner dies – is the key difference, and it’s worth getting right when you open the account, not after.
- Joint Tenants with Rights of Survivorship (JTWROS): Both partners have equal rights, and the survivor automatically receives the deceased partner’s share. It’s also the default for most joint accounts, according to the Consumer Financial Protection Bureau.
- Tenants in Common: The deceased partner’s share goes to their estate rather than automatically to the surviving partner, and shares can be unequal. Useful for couples keeping prior assets distinct, though the FDIC notes this setup is rare for bank accounts, so ask your bank.
- Community Property accounts: Available only in some community property states. Both partners own the account, so ask your bank how ownership and survivorship work.
*Payable-on-death (POD) or transfer-on-death designation: These can be applied to an individual account, and gives the survivor the money without giving the partner access while both are alive. You can establish this through the account’s financial institution with a form, and it doesn’t cost anything extra. Keep in mind that this bypasses probate and anything outlined in a will.
The same structures apply whether you’re opening a joint checking account for everyday bills or a joint savings account for shared goals.
What to know before opening a joint account
Access and ownership
Because either owner can usually move or withdraw money on their own, the account runs on trust and agreed rules. Decide together which withdrawals need a conversation first. That’s a feature when you trust the system and a risk when you haven’t agreed on the rules.
FDIC insurance
FDIC coverage applies per depositor, per bank, per ownership category. For joint accounts, the FDIC insures each co-owner up to $250,000, so two equal co-owners have up to $500,000 of coverage in the joint category at one insured bank, double what either would have alone.
Debt and responsibility
If a joint account comes with an overdraft line or other borrowing, your account agreement decides who’s responsible. Ask your bank before you both sign.
A partner’s personal debts can reach the account too. The Consumer Financial Protection Bureau notes that if one account holder owes money, the creditor can try to collect from money in the joint bank account.
A joint account’s full balance can count against asset limits for Social Security Income, Medicaid, disability, and some state programs, so a partner who receives means-tested benefits should talk to the program before being added to an account.
Taxes and retirement
One perk for married couples filing jointly: if one spouse has little or no taxable compensation, the IRS allows a Spousal IRA, so both partners can keep building retirement savings. Combined contributions can’t exceed the taxable compensation reported on the joint return (IRS Publication 590-A). This is only available for married couples.
Can unmarried couples open a joint bank account?
Yes, you don’t need to be married to open a joint bank account. The bigger question is whether your agreement is clear enough to protect both of you. Without marriage, divorce property rules generally won’t decide how to divide the account if you split.
Before opening one, agree on:
- What the account is for, and which bills it covers
- How much each partner contributes, and whether that’s equal or proportional
- Whether either of you can withdraw money without a conversation first
- What happens to the balance if the relationship ends
- Whether larger shared assets – a security deposit, a car, a pet – need a written agreement
None of this is unromantic. It’s the same clarity married couples get from state law, written down by the two people it actually affects.
How to choose the right account setup
If this sounds like you | Consider this setup |
You want full visibility and shared decision-making | Fully joint |
You want shared bills covered but personal spending private | Hybrid |
Your incomes are very different | Hybrid with proportional contributions |
You’re unmarried and share only a few expenses | Separate, or one limited shared account |
You’re combining finances later in life | Hybrid or separate |
You have complex debt, business finances, or prior assets | Hybrid or separate, with clear written agreements |
You want one simple household budget | Fully joint |
Still deciding? Use this flowchart in your next money conversation with your partner:

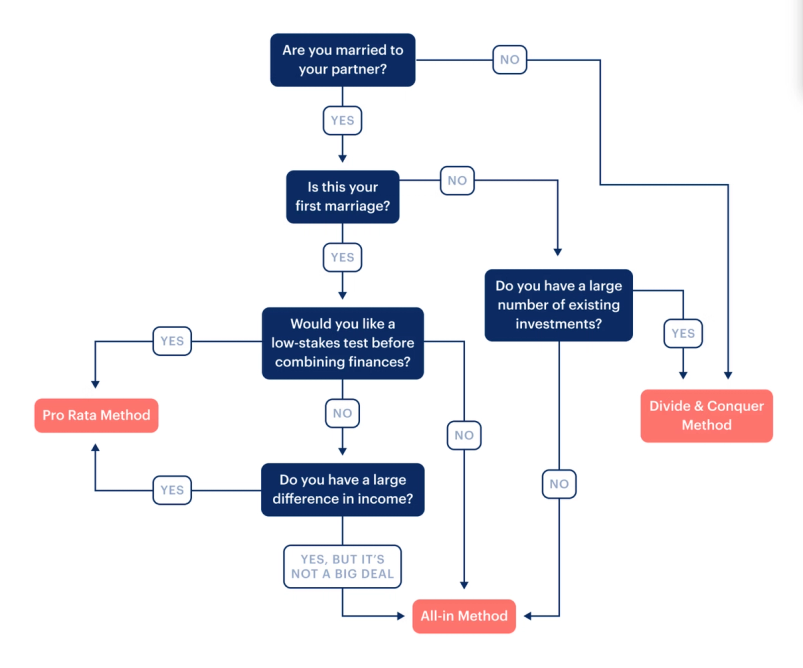
And if you’re unsure, start small: open one limited shared account for recurring bills, keep everything else separate, and revisit in three months. No setup is permanent.
Money questions to ask before opening a joint account
Run through these together once, out loud, before money moves:
- Which bills get paid from the joint account?
- How much does each partner contribute each month?
- Are contributions equal, or based on income?
- What size purchase needs a conversation first?
- How much personal spending money does each partner keep?
- What happens if one of you earns less for a stretch?
- How are debt payments handled?
- How often will you review the account together? (Monthly is a good default, during which you should review your net worth and goal progress.)
- What happens to the account if the relationship ends?
Ten minutes on these questions now prevents most of the conflicts joint accounts get blamed for later.
Choose the setup that fits your household
A joint account for couples is a tool, not a milestone. Some households work best fully combined, some fully separate, and many land in between – and all three are legitimate choices, not compromises.
Two decisions matter more than the account structure itself. First, make the system explicit: which expenses are shared, who contributes what, what stays personal, and when you’ll review it. Second, keep shared visibility regardless of structure. Fully joint, hybrid, or separate, both partners should be able to see the same household picture and make decisions from the same facts.
In Monarch, each partner keeps their own login under one household subscription. Mark each account or transaction as shared or as belonging to one partner, then filter reports and cash flow by owner. That way, a hybrid or fully separate setup still shows one household picture. One candid note: every connected account is visible to everyone in the household, so connect only what you’ve agreed to share.
You’ve already made the big decision: building a life together. The account setup is just the plumbing. Try Monarch free and set up your shared household view in an afternoon.
FAQ
Should couples have joint bank accounts?
Joint accounts work well for couples who want shared bills, budgeting, and savings goals managed from one place – 55% of Monarch member couples combine everything. But separate and hybrid setups are just as legitimate. The right choice depends on your incomes, debt, legal status, and how much independence each partner wants.
What are the pros and cons of a joint bank account?
Pros: shared bills paid from one place, faster progress on joint goals, no “who paid what” debates, and up to $500,000 in FDIC coverage for two co-owners at one bank. Cons: either owner can move money unilaterally, and a creditor of either partner can try to collect from the account. Untangling the account after a breakup is also messy without documentation.
Who owns the money in a joint bank account?
According to the Consumer Financial Protection Bureau (CFPB), generally everyone whose name is on a joint account can withdraw money, move funds, or close the account. The CFPB also notes that if one owner owes money, a creditor can try to collect from the joint account.
Is it better for married couples to have joint or separate bank accounts?
Neither is automatically better. Census data shows 77% of married couples with bank accounts held at least one joint account in 2023, but hybrid setups nearly doubled since 1996. What matters more is clarity: both partners understanding how bills, savings, debt, and personal spending are handled.
Can unmarried couples open a joint bank account?
Yes, you don’t need to be married to open a joint account. Because divorce property rules generally don’t apply if you split, unmarried couples should agree on the terms in advance. Cover contributions, withdrawal expectations, and what happens to the balance if the relationship ends – in writing for larger shared assets.
What happens to a joint bank account if one partner dies?
According to the Consumer Financial Protection Bureau, most joint accounts carry rights of survivorship, so the money passes to the surviving owner. With tenants in common, the deceased partner’s share passes to their heirs instead. See “Types of joint accounts couples can open” above to choose the right structure when you open the account.
What is a hybrid bank account setup for couples?
A hybrid setup means one shared account covers joint expenses – rent, utilities, groceries – while each partner keeps individual accounts for personal spending. Contributions can be equal or proportional to income. Among Monarch members, 18% of couples use this approach to balance shared responsibility with independence.
What should you look for in a bank for a joint account?
The account, not the brand. Look for no monthly fee or an easy waiver, separate logins and cards for each owner, the ability to set up automatic transfers from each partner’s individual account, and FDIC or NCUA insurance (which covers two co-owners up to $500,000 in the joint category). A joint account at the bank where one of you already banks keeps transfers instant; a separate institution keeps the shared money visibly separate. Either is fine, and a budgeting app that shows both partners the same picture matters more than which bank holds the account.
How should couples split bills if they have different incomes?
Three common approaches: split everything 50/50, split proportionally by income (the partner earning 60% of household income covers 60% of bills), or assign specific bills to each person. Proportional splits usually feel fairest when incomes differ significantly.