If you have an irregular income, want to keep strictly to your means, or want a detailed view of where every dollar goes, zero-based budgeting might be for you.
Zero-based budgeting is a strict budget style that assigns a destination for every dollar you make, from saving to spending. While it’s not the style for everyone, and can come with downsides, the structure and boundaries it provides to your spending can help you accomplish your goals and get disciplined about where your money is going.
This guide covers what a zero-based budget is, the pros and cons, who it works for, and how Monarch can help you build one.
What is Zero-Based Budgeting (ZBB)?
Zero-based budgeting (ZBB) is a budgeting method where you give every dollar of your monthly income a job, so your income minus your spending, saving, and debt payments equals exactly zero. With this method, you’ll justify and track each expense. This is a highly precise method of budgeting that sacrifices flexibility.
Zero-based budgeting can be a powerful tool not only for managing your spending, but helping you reach your financial goals. You can prioritize your savings, pay down debt by budgeting for extra repayments, and manage your overall financial picture in a detailed way that can help you grow your net worth and make sure your money goes where it has the most impact.
A Brief History of ZBB
Author Peter Pyhrr created zero-based budgeting in the 1960s. He developed the method, also known as zero-dollar budgeting, for business use while working as a manager at Texas Instruments in Dallas. He introduced the method to the public in a 1970 Harvard Business Review article, according to McKinsey.
Then-governor of Georgia Jimmy Carter later adapted it for government and public sector use, eventually adapting it to the federal United States budget when he was elected president.
Radio personality Dave Ramsey later popularized the method for personal use, especially for individuals with overspending habits or who needed more structure to their budgeting.
How to Build a Zero-Based Budget: A Step-by-Step Guide
Building a zero-based budget takes attention to detail and a clear picture of your monthly expenses. Here’s how to do it in six steps.
Step 1: Figure Out Your Take-Home Pay
To start, add up all of your regular take-home income, including salary, disability or Social Security, and retirement disbursements. If you’re self-employed, estimate how much taxes you would need to pay and assign it its own category, with your quarterly estimated payment being its own fixed line in your budget.
If you happen to make more or less than your usual income for the month, then you can adjust your budget later on (more on this later.)
Step 2: Figure Out Your Expenses
Next, list out your expenses for the month. Calculate the totals of what you typically spend, and divide out your expenditures into categories, such as groceries, utilities, entertainment, subscriptions, and so on. If you’re budgeting for a household rather than just yourself, the family budget guide walks through the categories a family actually needs.
Step 3: Divide Your Pay Out
Once you have your categories and your rough expense totals, assign each of your categories a dollar amount. Take into account both your income and your usual monthly expenses when you do this. For example:
- Rent: $1,580
- Insurance: $65
- Auto payment: $250
- Student loan payment: $200
- Groceries: $400
- Entertainment: $50
- Savings: $100
It can be helpful to assign out your essential expenses first, so that you can prioritize having enough funds for those, and dedicate the remainder to less-critical categories.
As well, be sure to include a “buffer” category for when your expenses are more than expected, like getting a bigger-than-expected electricity bill after a heat wave. Surprises are the norm, not the exception: in the Federal Reserve’s 2025 household survey, 59% of adults had at least one major unexpected expense in the prior 12 months. A buffer line is how a zero-based budget absorbs that without borrowing.
Step 4: Make Sure Your Math Works
Once you’ve assigned out your categories, make sure that you haven’t gone into the negative or the positive. The key goal is to make sure you hit zero.
If you have some money left over, give it a job in this order: top up your baseline cash cushion (one month of net income or $2,500, whichever is higher), then any debt above 25% APR, then enough retirement contribution to capture your employer match, then your full emergency fund and debt above 7%. Only after that does it go to extra investing or discretionary categories.
If you need to reorganize your expenses, you may want to “freeze” certain categories if you can’t or don’t want to change the amount you’ve already assigned. Then, organize your spending around the remainder.
Step 5: Keep an Eye on Your Spending
If you need to make adjustments because of a lower income, be sure to account for spending that you’ve already done in each category, and if there are any “frozen” categories that you can’t change. If you’ve gone over, pull from your buffer category or from a category with money left. In Monarch, you can move your budgeted amounts between categories and your monthly total stays at zero.
If you need to pull from your savings for a non-monthly expense or an emergency expense, consider your withdrawal a one-time “salary” bonus, and assign the expense appropriately.
Step 6: Review Your Month and Start Anew
Once the month is over, it’s time to rebuild your budget. You can use last month’s budget as your starting point as a baseline for your expenses, especially for fixed expenses that don’t change from month to month.
The key with rebuilding your budget is making sure that every single dollar is accounted for. This is especially key if your salary changes from month to month, or if your expenses tend to be variable. By tracking every single dollar, you’re making sure you know where your money is going and that you don’t rack up debt, miss on savings goals, or overspend your income.
Zero-Based Budgeting Example
Here’s an example of how a zero-based budget gives every dollar a job.
This example budget starts with a monthly take-home income of $4,840.
For context, the average U.S. household spent $6,545 per month in 2024, according to the Bureau of Labor Statistics. Your numbers will look different, and that’s the point. Every line reflects your own priorities.
Rent | $1,350 |
Utilities | $250 |
Car payment and insurance | $500 |
Student loan repayment | $450 |
Groceries | $400 |
Gas | $150 |
Subscriptions | $40 |
Clothing | $50 |
Restaurants/Eating out | $150 |
Gifts | $100 |
Savings | $700 |
Investment | $500 |
Buffer | $200 |
TOTAL | $4,840 |
Zero-Based Budgeting with Irregular Income
If your income varies from month to month, a zero-based budget is ideal for making sure you’re not spending too much in one month and not leaving enough for your lean months.
There are two ways to do this:
- Budget last month’s income. If you’re paid at the end of the month, treat the previous month’s income as this month’s “salary,” so you never assign dollars you haven’t already earned.
- Pay yourself a fixed salary. Average your earnings over the previous 12 months and budget that fixed amount every month. In months you earn more, the surplus goes to a holding account; in lean months, you draw from it to bring yourself up to the fixed salary.
Either way, the test for a variable earner is annual, not monthly: Monarch’s guidance is to spend less than you earn over the year, which a fixed salary enforces automatically. (Keep in mind that this method needs a baseline emergency fund in place, since your holding account shouldn’t be mixed with your emergency funds.)
If the holding account grows beyond a few months of the gap, that surplus can be released to goals.
Pros and Cons of Zero-Based Budgeting
Zero-based budgeting isn’t for everyone. It’s generally best if you’re struggling to stop overspending, if you have irregular income, or if you generally want a lot of structure in your budget. Looking at the pros and cons can help you decide if ZBB is right for you.
Advantages of Zero-Based Budgeting
- Accounts for every dollar you spend
- Can be helpful for irregular incomes
- High amount of structure
- Can help you pay down debt
Disadvantages of Zero-Based Budgeting
- Inflexible
- Takes a lot of work
- Easy to go off track with variable expenses
Zero-Based Budgeting vs. Other Budgeting Methods
Zero-based budgeting is only one of many budgeting strategies available. If you’re considering ZBB, here are a few ways it compares to other methods.
Zero-Based Budgeting vs. the 50/30/20 Rule
The 50/30/20 rule is when you assign 50% of your income to needs, 30% to wants, and 20% to savings and investments. While you can assign individual categories a dollar amount, in general, it’s less detailed than a zero-based budget.
Zero-Based Budgeting | 50/30/20 |
Strict allocation to designated categories | More open-ended with how you allocate funds |
High amount of structure and detail | Less structure and detail |
Requires a high degree of planning | Requires a lower degree of planning |
Best for managing overspending or an irregular income | Best for structure with some flexibility |
Zero-Based Budgeting vs. the Envelope Method
The envelope method is similar to the zero-based budget in that you divide out your income into categories with set limits. In the envelope method’s case, each “envelope” receives a set amount, with a hard limit on how much you can spend out of the envelope once the funds run out. The envelope method does allow for a bit of flexibility, as you can move funds between envelopes as needed.
If there are any funds left in the envelope after the month, instead of being dedicated to a “job” like the zero-based budget, they can be rolled over into next month’s envelope or put into savings. In Monarch, you can get the best of both by turning on rollover budgets for specific categories, so leftover grocery or gift money carries into next month instead of disappearing.
Zero-Based Budgeting | Envelope Method |
Highly structured with hard caps on spending | Highly structured with hard caps on spending |
Strict allocations for where money goes | More flexible allocations for where money goes |
You assign leftover funds to a category | Leftover funds can be moved, saved, or rolled over |
Best for managing overspending or an irregular income | Best for managing overspending |
Zero-Based Budgeting vs. Reverse Budgeting (Pay Yourself First)
A reverse budget, or the Pay Yourself First System, is the ultimate flexible budget. With this budgeting system, you pay yourself first by setting aside money for savings and investments, and then allocate the rest to your usual bills and expenses.
Compared to a ZBB, reverse budgeting is extremely flexible and doesn’t require as much structure or planning. While this can be great if you want a more open-ended budget, if you find yourself overspending or not having enough to cover your bills at the end of the month, then a ZBB might be better for you.
Zero-Based Budgeting | Reverse Budgeting |
Focused on managing overspending | Focused on prioritizing saving |
Highly rigid and structured categories and caps | Highly flexible in where you allocate your spending |
Requires intensive planning | Requires fairly minimal planning |
Best for managing overspending or an irregular income | Best for flexibility and saving/investing |
Tips for Sticking to Your Zero-Based Budget
Staying on track with a zero-based budget takes discipline and a bit of forethought. Here are our top tips for keeping to your budget.
- Track in real time. Use platforms like Monarch to track your transactions as they happen, giving you live information on your spending.
- Set alerts for overspending. Set threshold alerts on your card and budgeting apps that will notify you if you’re getting close to your category limits.
- Review your budget weekly and monthly. Frequent check-ins will help you keep an eye on your income and categories and allow you to readjust as needed.
- Limit yourself to physical cash. If you’re having a hard time managing expenses on your card, consider bringing physical cash when you go out, which will present a physical limit on your spending. Be sure to keep logging your cash transactions so you can track your spending.
- Build a support system. Let your friends and family know that you’re keeping your spending in check, and advocate for activities that will help you stick to your budget, like a picnic in the park instead of eating out.
- Have an emergency fund in place. According to the Federal Reserve, 63% of U.S. adults would cover a $400 emergency expense with cash or its equivalent, so more than a third would not. An emergency fund is what keeps a real emergency from blowing up the whole budget. Start with the baseline: one month of net income or $2,500, whichever is higher, in its own account, separate from the in-month buffer category. Then build toward a full fund sized to your household’s risks.
- Give yourself room for fun things. Even on a strict budget, it’s important to give yourself a fund to have fun. Managing your spending in this way is better than trying to get rid of it entirely.
How to Build a Zero-Based Budget in Monarch
Here’s how to set up a zero-based budget in Monarch in five steps.
1. Link Your Accounts
Your first step is to link your bank and card accounts. Be sure to link your charge accounts and the accounts where you receive your pay. Monarch will track your transactions and log them, automatically applying them to your budget.

2. Select the Category Budget Option
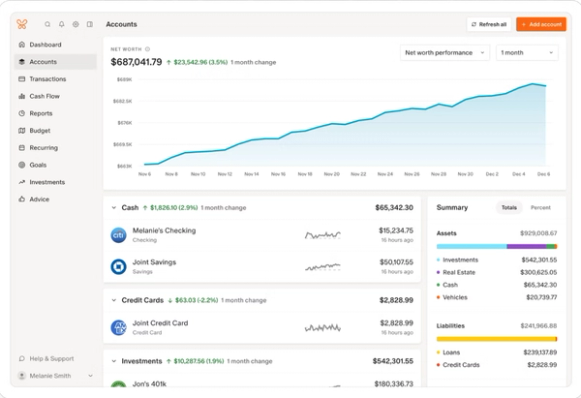
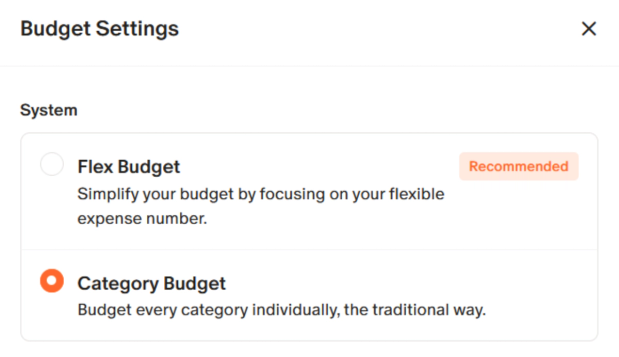
Next, go to your budget tab, select Settings (the little gear in the top-right corner) and select the option for category budget.

3. Select Your Categories
Next, choose the categories you want to budget for. Monarch has 60 default categories to choose from, with options to edit names and icons. You can also add custom categories.
If you don’t want to use a default category, you can remove it from your budget by clicking on the gear next to the name.

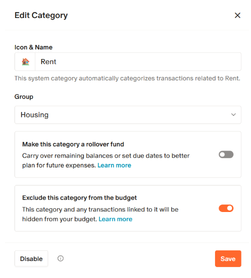
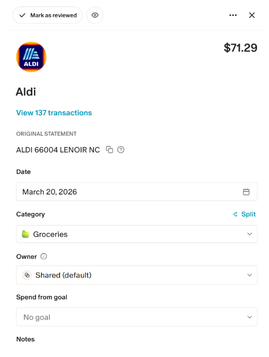
Monarch will assign categories based on your transaction merchants. You can review transactions by clicking on each category, and change the category and rules by clicking on the transaction.

4. Assign Dollar Amounts
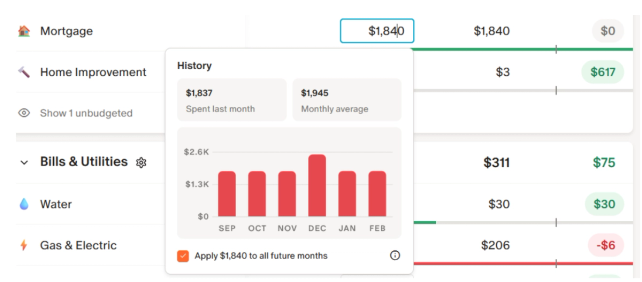
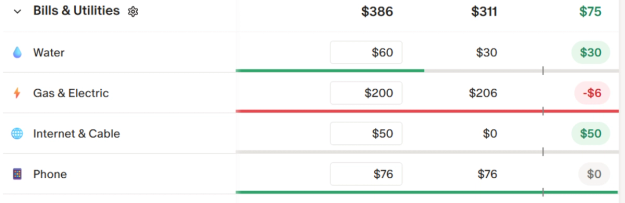
Once you have your categories set, you can assign your budgeted amount to each category by clicking on the text box next to the category name.
The first time you open your budget, Monarch fills in each category with your average monthly spending from the last six months, so you start from real numbers instead of guesses. Edit any of them to fit your plan.

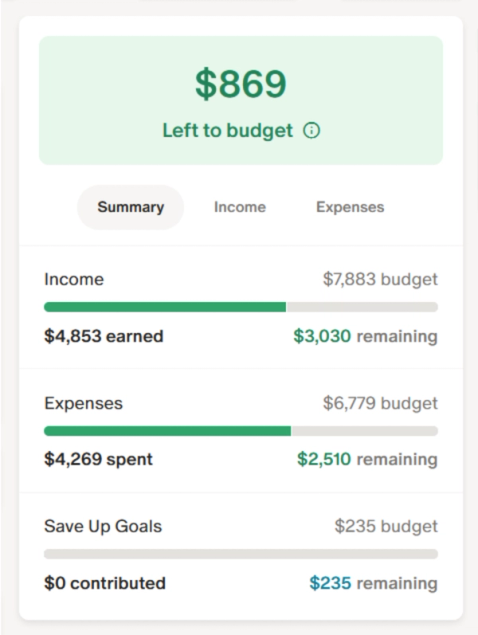
As you budget out your categories, Monarch will inform you of how much you have left to budget, allowing you to track how much you have left to allocate.

5. Track and Adjust as You Go
Once you have your budget and expenses set, you’re good to go. Monarch will track your transactions for you and alert you if you’ve gone over any of your parameters. You can access Monarch on your desktop or through the mobile app, and keep an eye on your categories to make sure you’re not going over.

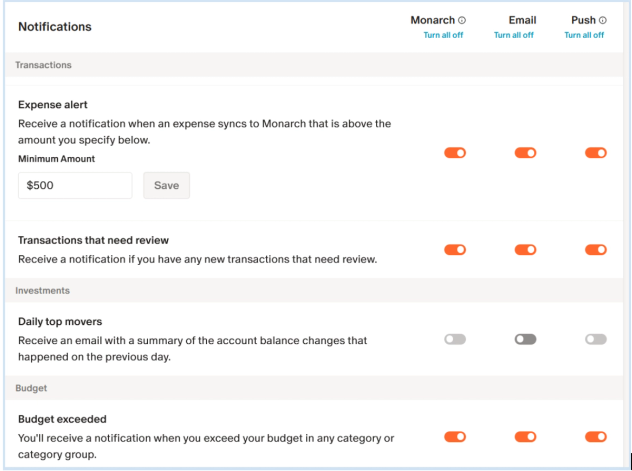
You can add custom alerts and notifications for when you exceed your budget, or when a transaction goes above a certain threshold, in the main settings option to the top left under “Notifications.”

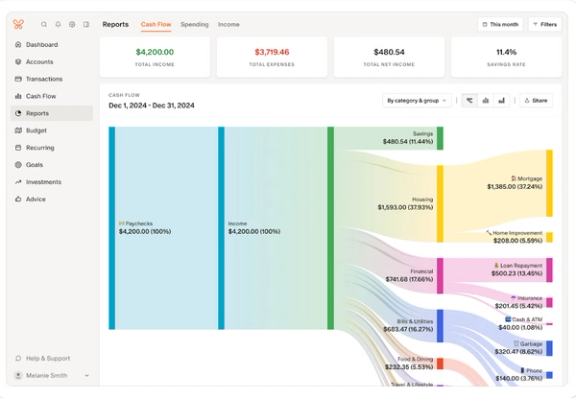
If you need to adjust a category, you can edit your budget any time from anywhere. For big-picture analysis, Monarch offers monthly reports and cashflow at a glance to keep you informed about how much you’re saving each month, and where your money is going. You can also project your cashflow and expenditures into the next month, allowing you to plan ahead.

Want a zero-based budget backed by your real numbers, with tracking that updates as you spend? Try Monarch for free.
The Bottom Line: Is Zero-Based Budgeting Worth It?
Zero-based budgeting, while work-intensive and highly structured, can be a good way of managing your finances when you need to make every dollar count. Because all of your income is accounted for, a ZBB can help you manage overspending and designate funds for essentials, savings, and the things that matter to you.
FAQs
Does zero-based budgeting mean I spend all my money?
Not necessarily. While you need to assign a place for every dollar, you can designate funds to savings or investments. In fact, it’s a good idea to set aside some cash each month to contribute toward your emergency fund or other financial goals.
Is a zero-based budget the same as living paycheck to paycheck?
No. Both can end the month at $0, but a zero-based budget gets there on purpose, with savings, debt payments, and a buffer built in. Living paycheck to paycheck means running out because of circumstance, with no margin for surprises.
How do you make a zero-based budget?
Start from take-home pay, not gross. Fund essentials first, then debt minimums, then savings and goals, then wants, and keep assigning until the unallocated number reads zero. The two habits that separate people who stick with it from people who quit are a buffer category for surprises and a monthly rebuild rather than copying last month forward.
What makes a budget a zero-based budget?
One test: income minus every assignment equals zero before the month starts. A budget where you track spending against limits but leave income unassigned is a category budget. A budget where savings is “whatever’s left” is a reverse budget. It becomes zero-based only when every incoming dollar has a named destination, including the dollars you’re saving.
Why is zero-based budgeting considered one of the most effective methods?
Because it removes the gap where overspending hides. In most budgets, money that isn’t explicitly assigned drifts into whatever category is easiest to spend from. Zero-based budgeting closes that gap by making savings, debt payments, and the buffer line items that are funded first, so spending has to fit around them rather than the other way around. The trade-off is the time it takes to rebuild the plan each month.
What is the 70-10-10-10 budget rule?
It’s a simpler split: 70% of take-home pay for living expenses, 10% to savings, 10% to investing or extra debt payments, and 10% to giving. Like 50/30/20, it sets proportions rather than dollar amounts, so it’s faster to set up than a zero-based budget but far less precise. You can run a zero-based budget inside those proportions by assigning the dollars within each slice.
What categories should a zero-based budget include?
It depends on your needs, but most zero-based budgets include categories for the expenses you plan on having for the month, including the mortgage/rent payment, utilities, groceries, gas, debt repayments, subscriptions, entertainment, and so on. You’ll also want to dedicate a category to savings and investments, as well as a “buffer” category in case you need to dedicate extra funds to a category.
Can I use zero-based budgeting with irregular income?
It’s actually well-suited to this, since you have to be aware of how much income you’re working with and make sure you don’t exceed what you’re bringing in. You can base your budget on the month’s previous income, the month’s expected income, or an average you calculate based on historical data.
How is zero-based budgeting different from traditional budgeting?
Traditional budgeting usually starts from last month’s numbers and adjusts up or down. Zero-based budgeting starts from zero every month, so each expense has to earn its place in your plan again.
How is zero-based budgeting different from the 50/30/20 rule?
The 50/30/20 rule has much looser categories and more flexibility in how you allocate your dollars, with more broad categories and no specific dollar amounts dedicated to any one purpose.
Is zero-based budgeting the same as the envelope system?
Not quite. While the envelope system does have hard limits on spending, it generally works with the assumption that you might have some funds left over, which can be rolled over into the next month or saved. Zero-based budgeting is stricter: every dollar gets a specific purpose, with nothing left over.
How does Monarch support zero-based budgeting?
Monarch’s category budget lets you give every dollar a job, track each transaction against your plan as it happens, and see how much you have left to assign until you hit zero. Add as much or as little detail as you want.